
Publications
11 Sep 2026
Are Ports More Important Than Capitals?
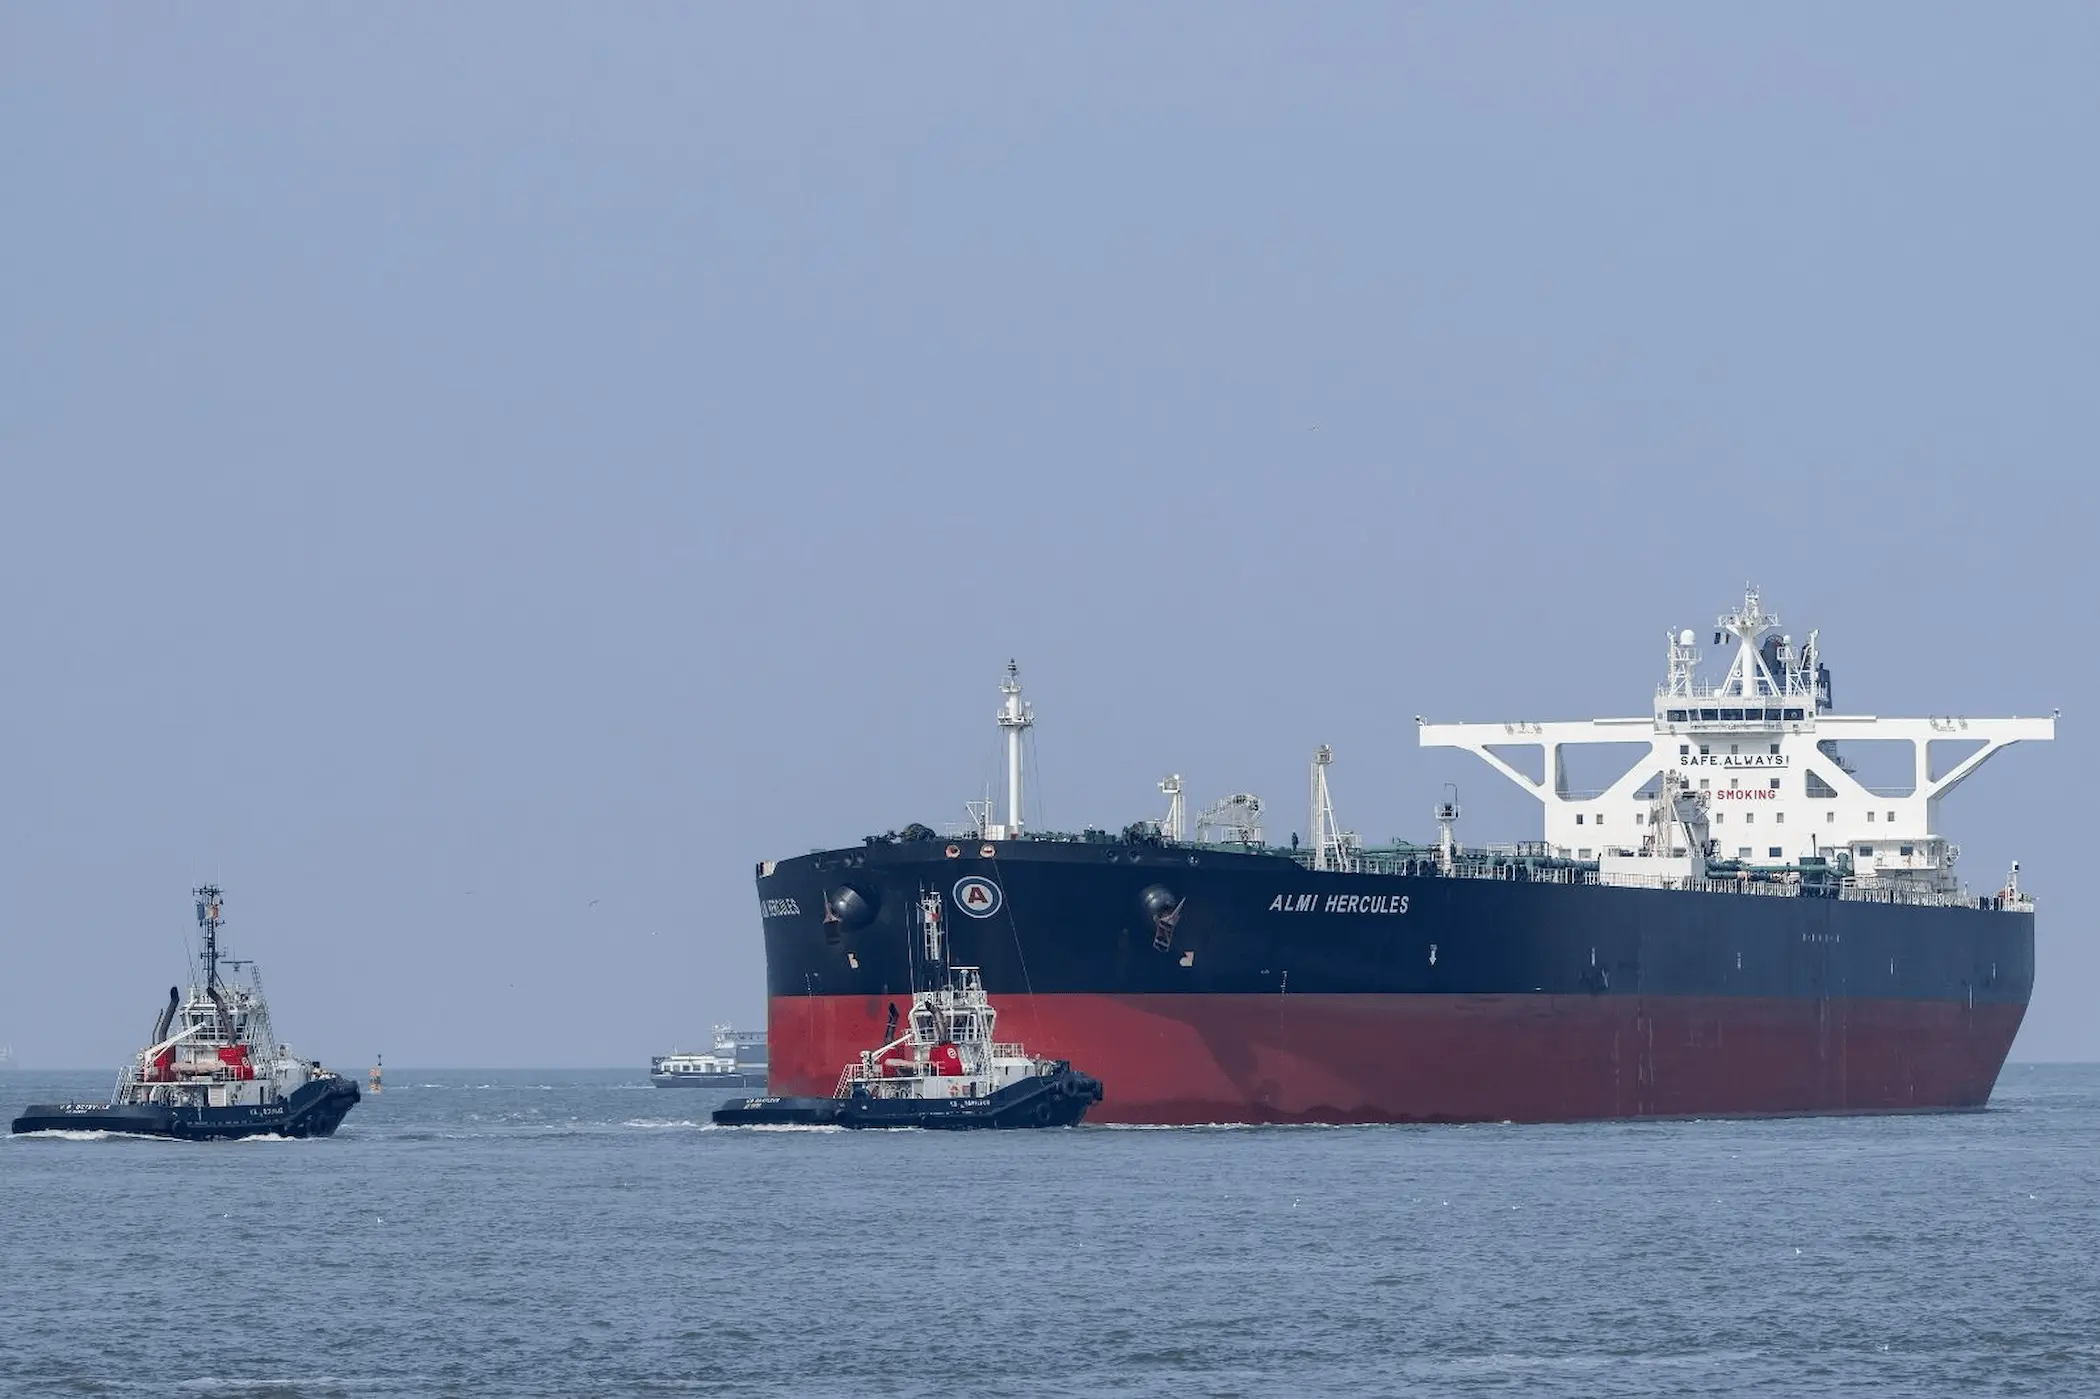
While political capitals retain legal and sovereign authority, seaports have emerged as the "functional capitals" of the modern state. These maritime nodes are where sovereign decisions are translated into material reality, controlling the flow of energy, food, industrial inputs, and data. With 80% of global trade volume and 70% of its value moving by sea, the disruption of a major port can rapidly paralysise a nation's economy and military logistics, demonstrating that port power is highly consequential and systemic.
Port power is relational, depending on factors like geographic position, network centrality, industrial depth, and digital architecture. The global port network is highly concentrated, with less than 5% of ports handling half of the global maritime trade, creating a paradox where extreme efficiency leads to profound systemic vulnerabilities. This concentration makes ports susceptible not only to physical blockades or congestion but also to cyberattacks and climate change, necessitating robust resilience strategies.
Furthermore, foreign investment in port infrastructure carries significant geopolitical implications, moving beyond simplistic narratives of "debt-trap diplomacy". Long-term concessions and operational control can create strategic dependencies, even without outright asset confiscation. Additionally, modern ports possess a dual-use nature, where commercial facilities can provide latent military option value, blurring the lines between economic integration and naval expansion. Ultimately, true national power lies in the effective integration of the political capital's authority with the strategic port's physical capabilities.
This publication was written in August 2026
Programmes
10 Sep 2026
Orbital Data Centres and the Limits of National Jurisdiction over Technology Firms
The largest technology firms are moving their data centres into low Earth orbit, having pushed terrestrial infrastructure to the physical and environmental limits of what it can supply in power, cooling and land to an artificial intelligence sector whose demands keep compounding. SpaceX has set the fourth quarter of 2027 for the launch of its first generation of computing satellites, targeting one gigawatt of orbital data centre power capacity in that same year and one hundred gigawatts by 2030. The scale of the pressure behind that schedule is visible in the wider market, where global data centre demand is estimated to require investment approaching €5.7 trillion before the decade closes.
What presents itself as an engineering migration is in substance a redistribution of sovereign authority. Moving processing beyond national territory removes technology firms from the reach of the data localisation rules, compliance regimes and tax frameworks that states have spent a decade constructing. For Arab states the challenge is immediate. Having invested heavily in domestic digital infrastructure and imposed strict data residency requirements, they now face the prospect that the server handling their citizens’ data sits five hundred kilometres overhead, beyond the enforcement reach of their courts.
This analysis therefore examines the economics of moving computation into orbit and the limits of its viability; traces the legal gap that allows technology firms to shelter behind the jurisdiction of the state of registry in order to avoid the laws of every other state; assesses the risks of monopolistic concentration and the environmental costs borne collectively; and identifies the regulatory instruments available to Arab states in defence of their digital sovereignty, chief among them the management of radio-frequency spectrum, satellite landing rights and the supervision of ground gateways.
Programmes
27 Jul 2026
Trump’s Prize: How the July 2026 Tariff Package Installed the Middle East as a Global Manufacturing Hub
The global trading system underwent a fundamental transformation in July 2026, as the United States abandoned limited sector-specific protection in favour of a complex, multi-tiered tariff architecture that turned access to its domestic market into an instrument of economic and political pressure. Four major decisions converged within that single month. The first was the outright repeal of the de minimis exemption, which had allowed small consignments valued below eight hundred dollars to enter the country duty-free. The second was the application of the Section 301 forced-labour tariffs across two distinct bands, imposing 10% and 12.5% according to the compliance record of each partner state. The third was the activation of Section 338, a statutory provision that had lain dormant since the 1940s, to levy 50% duties on a range of Canadian goods. The fourth was the approval of a phased escalation reaching 200% on imports of generic pharmaceuticals.
The consequences of this package extended well beyond the raising of customs duties. They amounted to a comprehensive re-engineering of rules of origin and customs compliance requirements, which in turn altered the cost calculus of every manufacturer and supplier across global supply chains. This new reality pushed firms to search for alternative routes designed not merely to reduce transport costs, but to change the identity of the country of origin itself and so escape punitive duties. That search is precisely what turned the Middle East from a transit corridor into an industrial and logistical node positioned to play a pivotal role on the new map of world trade.
This analysis therefore aims to unpack the effects of the July 2026 package across three connected levels: its domestic cost to the American economy in terms of inflation, compliance friction and the feasibility of reshoring; the realignment of trading partners and the trade diversion and origin leakage that follow from it; and finally its direct implications for the economies of the Middle East and North Africa, together with quantitative estimates of price, investment and shipping trends through the end of the decade.
Programmes
23 Jul 2026
Bab al-Mandab at the Heart of the Crisis: Will the Houthi Blockade Push Pakistan into a Confrontation with Iran?
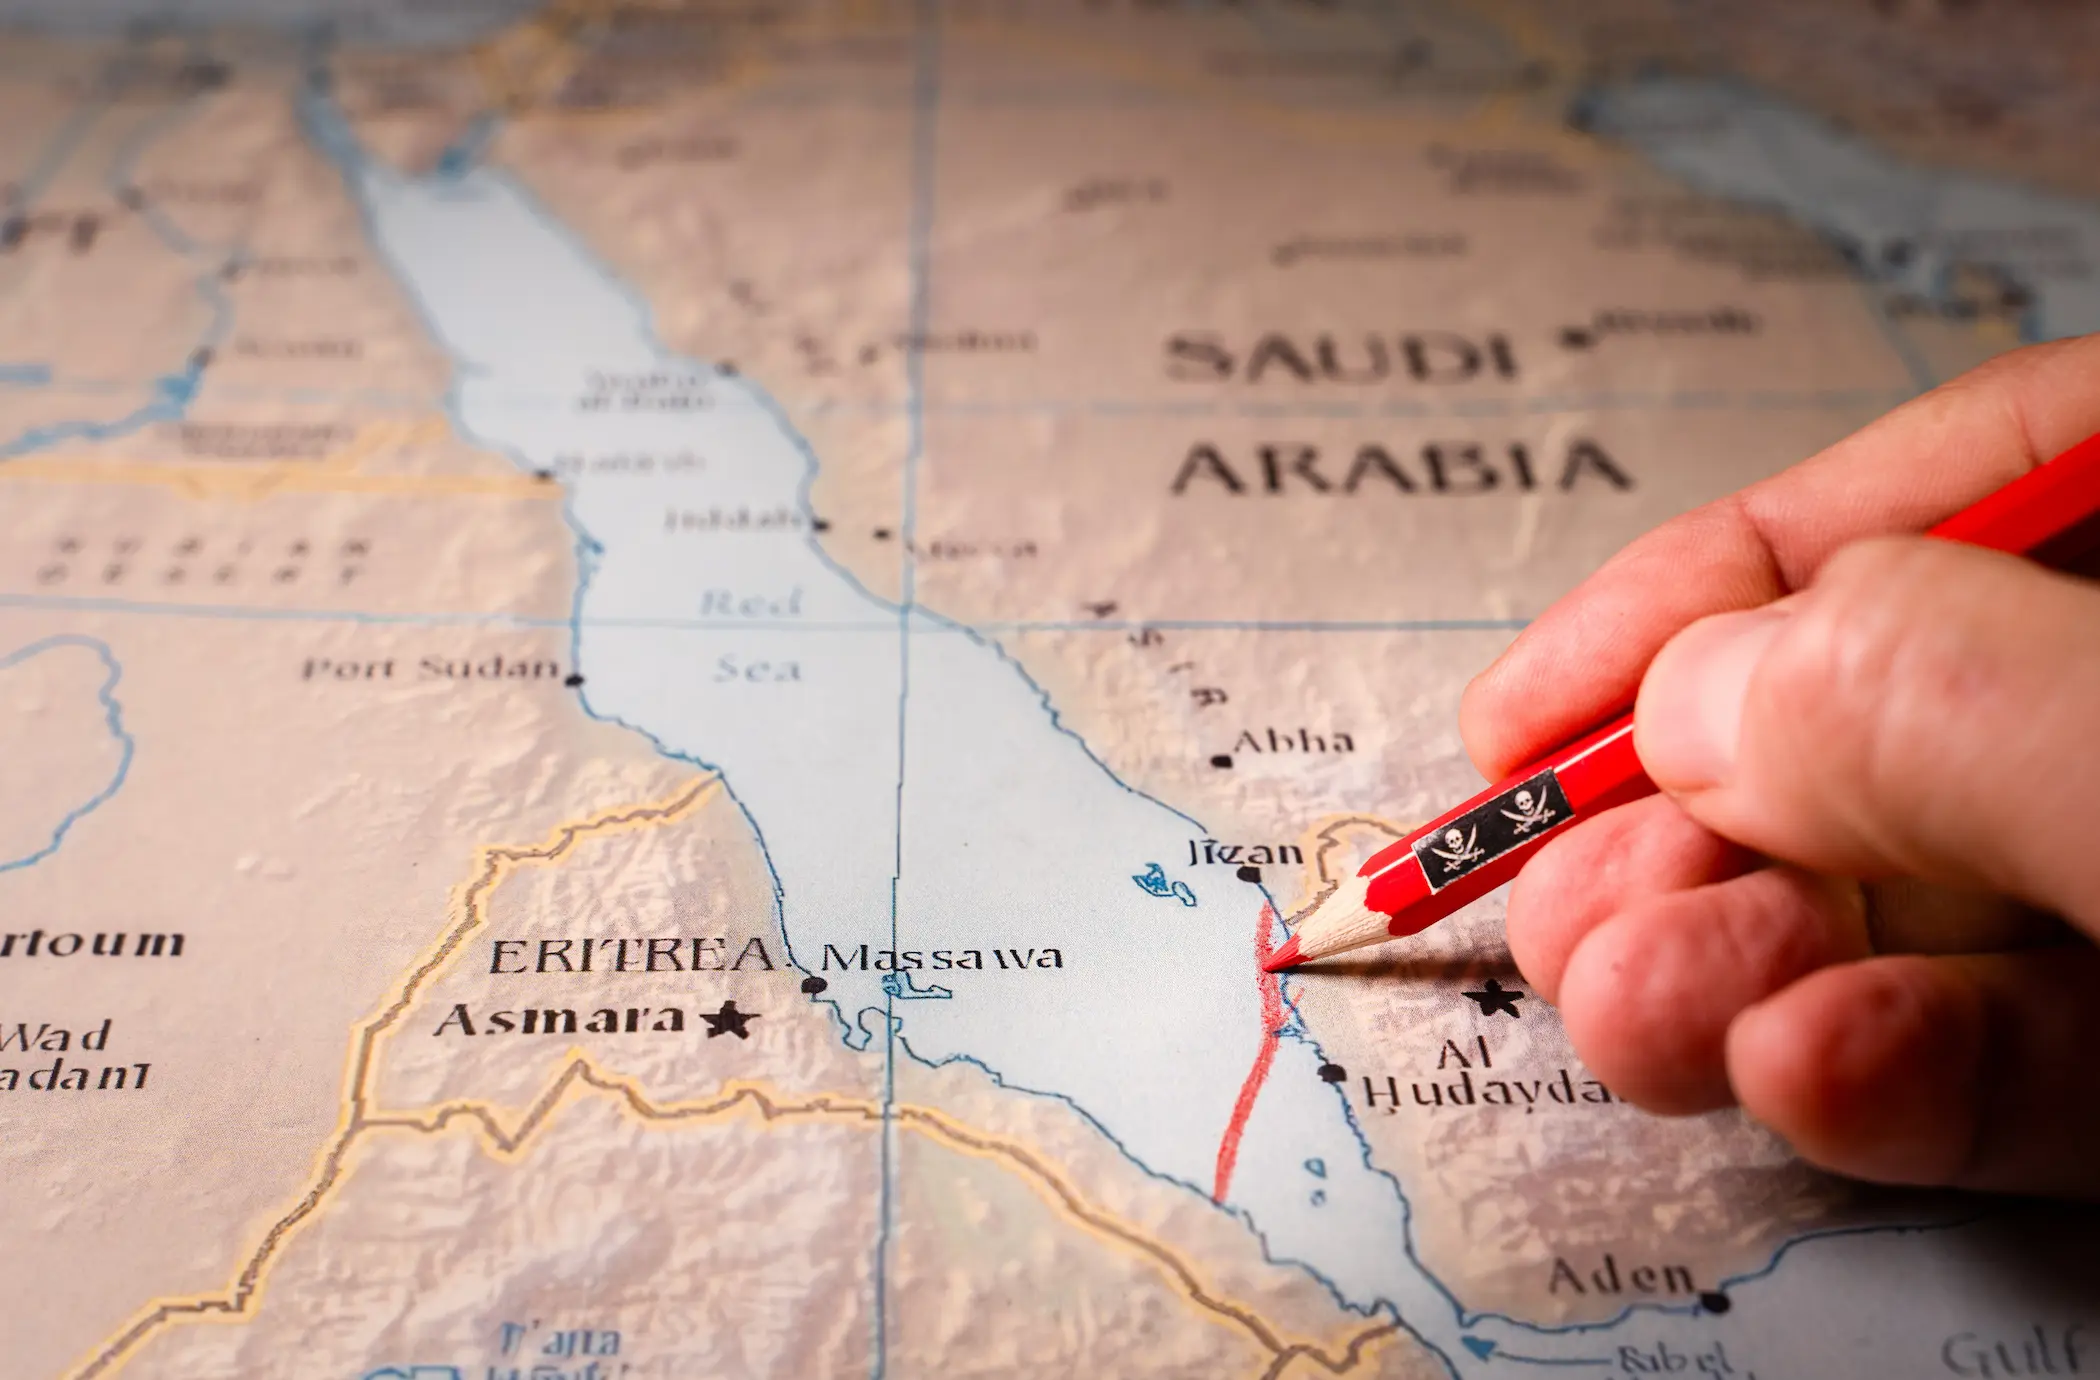
The Middle East is witnessing a new geopolitical crisis centred on the Bab al-Mandab Strait after Yemen’s Houthi movement announced on 20 July 2026 the imposition of a naval blockade on the Kingdom of Saudi Arabia, in application of a principle the group terms “blockade for blockade”. The measure comes as a direct response to the restrictions Saudi Arabia has placed on the airports and ports lying under Houthi control, most notably Sanaa Airport and the ports of Hodeidah, and the decision followed a military escalation that included strikes on Sanaa Airport and the launching of missiles and drones towards Saudi airports.
Through this closure the Houthis seek to transfer the cost of the blockade from the Yemeni interior to a corridor vital to Saudi Arabia in the Red Sea and the Bab al-Mandab Strait, by closing the strait to vessels flying the Saudi flag or bound for the Kingdom. The closure also coincides with the disruption affecting the Strait of Hormuz as a result of the ongoing Iranian–American war, where the Revolutionary Guard’s interception rate of vessels transiting the strait has reached some 89 per cent. This has driven the Kingdom over the past four months to reroute its oil exports westwards, moving 4.5 million barrels of oil a day through a pipeline to the port of Yanbu on the Red Sea in order to provide an alternative passage, an increase of close to fivefold on the period before the war began.
On another front, Pakistan faces a complex strategic position as a result of these developments, since Islamabad is bound by a mutual strategic defence agreement with the Kingdom of Saudi Arabia signed in September 2025, alongside the presence of Pakistani forces stationed in the Kingdom. The agreement stipulates that any aggression against either state is deemed an aggression against the other, while Islamabad simultaneously performs the role of diplomatic mediator between the United States and Iran, having sponsored the signing of a ceasefire memorandum of understanding between the two parties in June 2026. In this context, Pakistani officials regard attacks on Saudi Arabia as a red line, which makes the naval blockade not merely a problem touching Saudi security but a direct test of Pakistan’s ability to balance its role as mediator with Tehran against its military commitments towards Riyadh. This tension places the Pakistani leadership before a clear challenge and raises an important question as to whether it will persist in its neutral position, or move towards a firmer stance should the crisis develop into a regional confrontation affecting the interests of its Saudi partner.
Programmes
23 Jul 2026
Closure Upon Closure: The Potential Impact of Houthi Threats to Saudi Shipping at Bab al-Mandeb
The events of 2026 have placed global energy markets before an unprecedented test of their resilience. When the effective closure of the Strait of Hormuz in February removed roughly 13 million barrels per day (mb/d) from available supply, Saudi Arabia redirected most of its exports westward to the Red Sea — only to find that outlet itself imperiled when, on 20 July, the Houthis threatened a naval blockade of the Bab al-Mandeb strait aimed squarely at Saudi shipping. For the first time in its modern history, the Kingdom's oil found itself exposed between the two maritime corridors it straddles, and the question “What if navigation through Bab al-Mandeb is severed?” shifted from a theoretical exercise to an operational probability. The answer, however, is not a single figure: it hinges on the scale of the shortfall, the nature of the cargo held back, and the market's capacity to reroute it.
This analysis therefore sets out to quantify the impact of a Bab al-Mandeb closure across three graduated halt scenarios; to unpack the mechanism by which the shock travels from cargo entrapment to a price spike; to trace its non-price consequences for refined products, aviation, and maritime shipping; and to arrive at the fiscal paradox that leaves the gravest harm to Saudi Arabia latent in the intermediate scenario rather than the full halt.
Publications
4 Jun 2026
The Arabness of Hormuz Strait: The Name, the Land, and the People
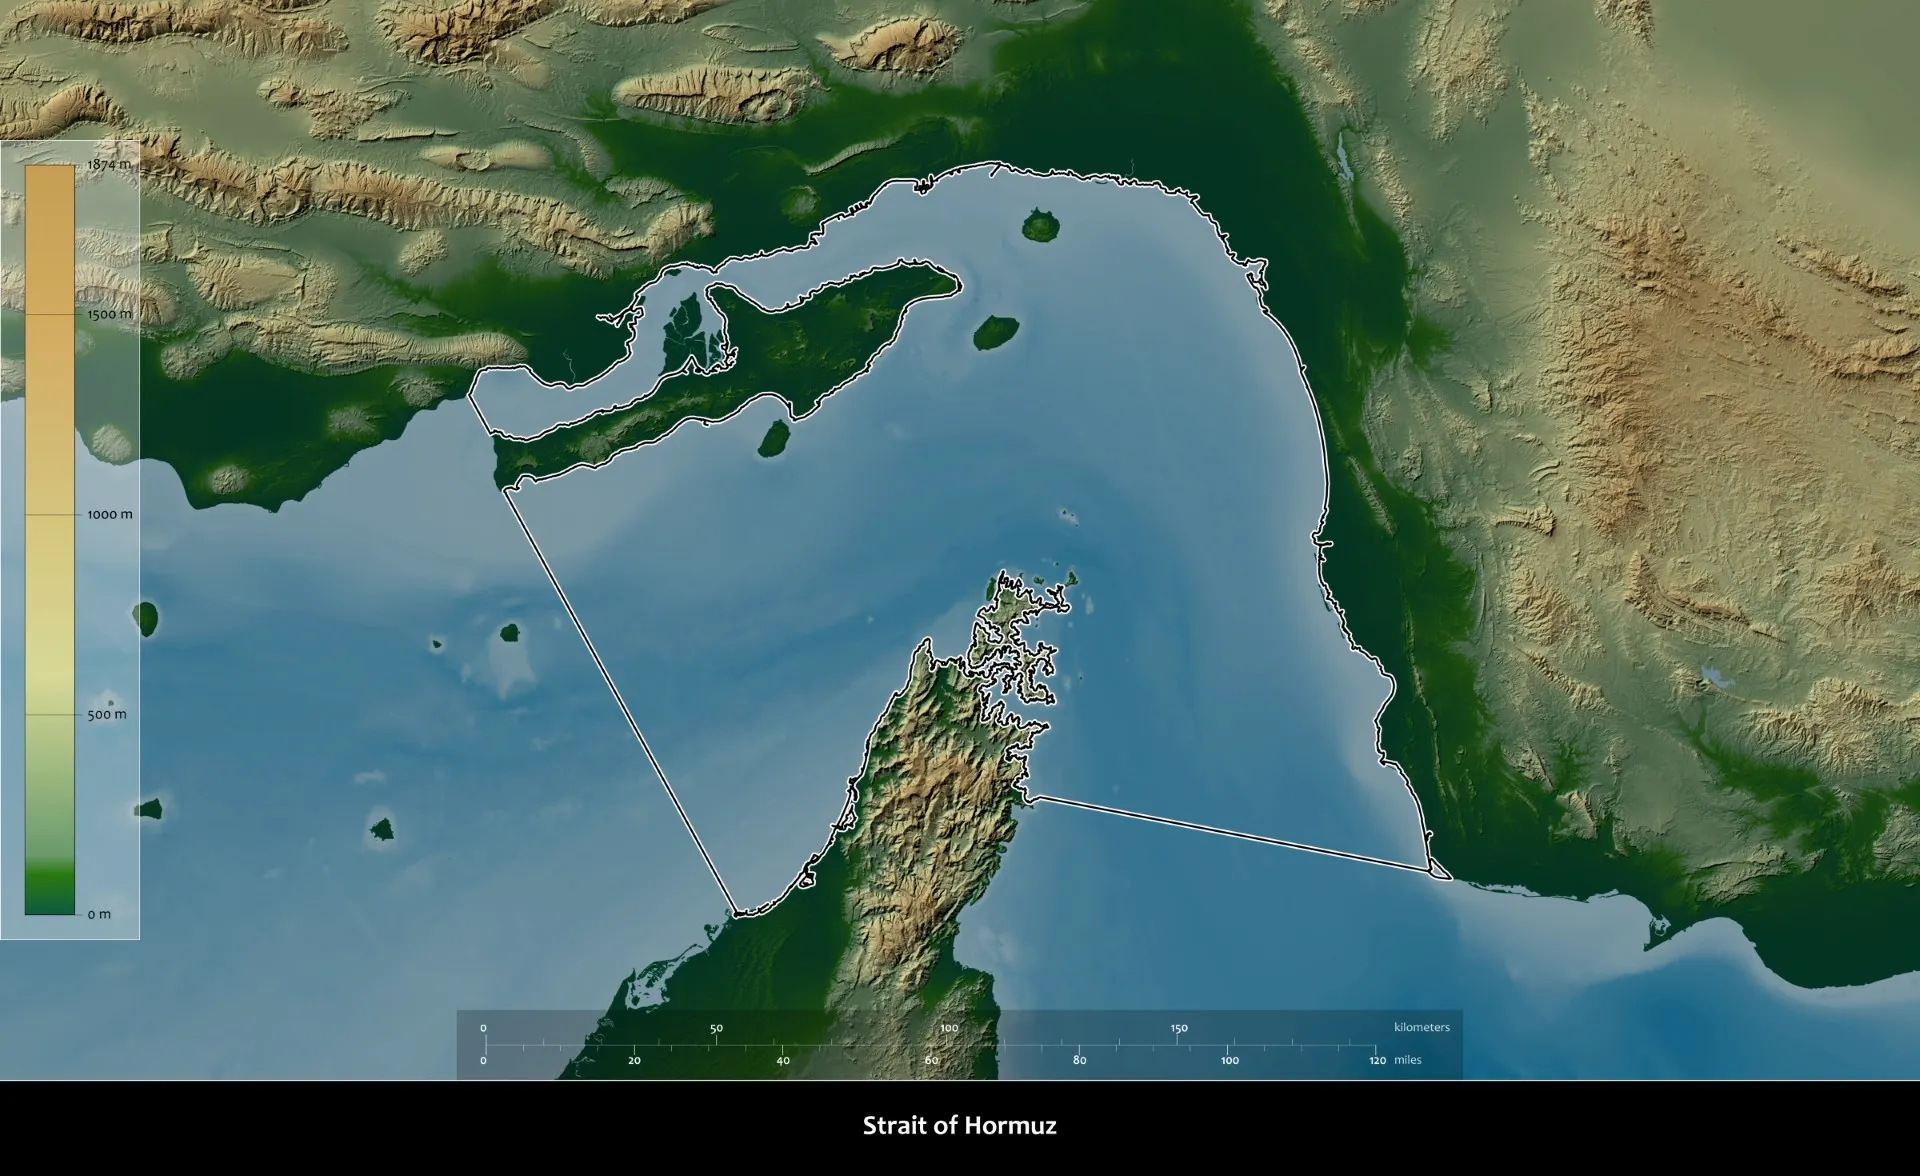
The Strait of Hormuz is, in the modern imagination, an energy chokepoint through which roughly a fifth of global petroleum and a comparable share of liquefied natural gas transit. Yet this narrow waterway carries a far older and more contested significance, one bearing directly on questions of identity, sovereignty, and historical legitimacy in the Arabian Gulf.1 This study addresses three questions and resolves each on the basis of the documentary and archaeological record.
First, it traces the origin of the name “Hormuz”, surveying the principal etymological theories, subjecting each to critical scrutiny, and arriving at a reasoned synthesis. Second, it reconstructs the history of the Arab population on both shores of the Strait, marshalling demographic and documentary evidence to show that the enduring human substrate of the region was Arab throughout recorded history, while Persian authority was characteristically a governing superstructure rather than a settled population. Third, it situates the Battle of Chains and the defeat of the Sasanian commander Hormuz in its correct chronological place within that continuum and corrects the popular but mistaken belief that the Strait was named after him.
The central finding is that the Strait of Hormuz, far from being a frontier dividing an Arab world from a Persian one, functioned for five millennia as a connective maritime highway whose permanent population was overwhelmingly Arab in character, even during the long intervals in which a Persian imperial umbrella claimed nominal sovereignty over its northern littoral.
Programmes
19 May 2026
The Collapse of Trust in the Digital State
For decades, the systems that governments, banks, universities, and public institutions built to verify who someone is rested on a single foundational assumption that personal information, documents, and physical characteristics were difficult to convincingly fake. A Social Security number combined with a date of birth and a driver's license was, for most practical purposes, enough to establish identity.
That assumption has now been broken. The US recorded its highest number of data breaches in 2025 since tracking began, identity theft reports to the Federal Trade Commission rose nearly 20% year over year, and global fraud losses now exceed $534 billion annually. Generative AI, the same technology powering productivity tools and creative applications across the economy, has become a force multiplier for those seeking to deceive digital systems at scale. The speed, sophistication, and accessibility of these tools mean that the problem is no longer confined to the margins of financial crime. It has moved to the centre of a broader question about whether the digital infrastructure modern states depend on to function is as reliable as they have assumed.
Programmes
27 Apr 2026
Hungary as a Bridge: How Could Budapest become a Food Security Partner for the UAE?
Hungary has a strong and well-developed agricultural sector. Arable land and permanent crops account for 4.3 million hectares, of which approximately 130,000 hectares are irrigated. The main crops include wheat (0.9 million hectares), corn (0.8 million hectares), and sunflowers (0.7 million hectares). While pastures cover 0.8 million hectares and forests cover 2 million hectares, livestock production includes 2.8 million pigs and 33.8 million poultry.
The country’s economy is export-dependent, so many technological advancements and the easing of financial restrictions, such as VAT, were integrated across various sectors, helping improve products and increase profits. The agricultural sectors benefited greatly from such policies, where crops and livestock exports have increased throughout the years. Agricultural exports constituted 9.1% of Hungary's total exports in 2024, including commodities like grains and grain products (13%), animal feed (12%), meat and meat products (9%), dairy products (5%), and fruits and vegetables (5%). Hungary's pioneering role in the agricultural sector increases its prospects for adopting measures to address food insecurity while increasing the benefits for any country that cooperates with it.
Programmes
23 Apr 2026
Challenging Dollar Supremacy: Is the UAE Rethinking the Dollar Order?
For more than five decades, the petrodollar system has served as one of the central structural pillars of American financial supremacy. Since its establishment in the 1970s, the system has anchored the United States’ monetary power by ensuring that Gulf oil exports remain overwhelmingly denominated in United States dollars. Under this arrangement, Gulf producing nations receive American security guarantees in exchange for recycling their oil revenues into US Treasury securities and dollar-denominated financial markets—a self-reinforcing cycle that has entrenched the dollar’s status as the world’s foremost reserve currency and systematically reduced American sovereign borrowing costs for decades.
The United Arab Emirates has, historically, been among the most faithful participants in this arrangement. Its national currency, the dirham, remains pegged to the USD, and its extensive sovereign wealth funds are invested predominantly in dollar-denominated assets. Nevertheless, a convergence of recent developments—an armed conflict in Iran, severe disruptions to Gulf oil exports, and an acute domestic dollar liquidity constraint—has placed the UAE at an unprecedented geopolitical and financial crossroads.
Programmes
23 Apr 2026
From Resilience to Ascent: How the UAE Transforms Crises into Opportunity
Many analysts fall into a recurring methodological error when assessing the United Arab Emirates’ (UAE) position amid regional turbulence. They measure the country’s resilience by its geographical distance from centres of risk, overlooking its exceptional capacity for strategic reinvention in the face of crises. This misreading, in particular, lends early credibility to pessimistic narratives of a “decline of the Gulf”, narratives that quickly unravel under the weight of empirical evidence and the firmness of facts. The UAE has not navigated successive regional crises by relying on geographic insulation or external protection. Rather, it has done so through deeper, more enduring foundations: a demonstrated ability to convert shocks into substantive reform, and to elevate those reforms into sustained competitive advantage.
Accordingly, this analysis does not seek to downplay the scale of the challenges posed by a regional war that is casting a heavy shadow over the security of the Strait of Hormuz, maritime insurance markets, and investment flows. Rather, it offers a structured attempt to address three interrelated core questions: how has the UAE historically navigated major crises; how did it anticipate the current crisis by fortifying its infrastructure and economic systems to sustain resilience; and, finally, how should the present moment be understood, not as signalling the end of a development model, but as marking the transition to a more mature and deeply embedded position within the global economy.
Programmes
15 Apr 2026
From Doha to Washington: How Hormuz Redrew Global Gas Supply Chains
At the outset of 2026, the global natural gas market underwent a profound structural shift that eroded much of the stability built over years of rebalancing in the aftermath of the 2022 European energy crisis. Markets had been advancing towards a phase of relative supply abundance, underpinned by expanding liquefaction capacity in the United States (US) and large-scale Qatari projects. This trajectory was abruptly reversed on Feb. 28, 2026, when Operation Epic Fury triggered the most severe energy shock to confront the international system in decades. The US-Israel-Iran War and the closure of the Strait of Hormuz, removed nearly one-fifth of global liquefied natural gas supply from circulation within days.
This paper analyses the structural transformations in the global natural gas market induced by the crisis, tracing supply and demand dynamics before and after the outbreak of the conflict. It further evaluates the implications for key actors within the international energy system, including countries most exposed to global gas market volatility, such as Egypt and Jordan.
Programmes
13 Apr 2026
The Implications of the April 2026 U.S.–Iran Ceasefire on Oil Prices
On April 7, 2026, the United States (US) and Iran announced a temporary two-week ceasefire, following intensive diplomatic mediation led by Pakistan during a critical window of escalation. The conflict had erupted on Feb. 28, 2026, when the US and Israel launched coordinated military strikes targeting Iranian infrastructure. In response, Tehran moved to close the Strait of Hormuz to international commercial shipping, precipitating the most severe energy supply shock in modern market history.
The closure effectively paralysed approximately 20 million barrels per day that would ordinarily transit the Strait of Hormuz in peacetime, accounting for nearly a quarter of global seaborne oil trade. Under the terms of the ceasefire, Iran announced a conditional reopening of the strait, while the parties agreed to commence diplomatic talks in Islamabad on April 10. This analysis examines the full scope of the crisis and evaluates the prevailing oil price scenarios, drawing on lessons from comparable historical shocks to assess the fragility of the current environment and its potential trajectories.