
Publications
8 Oct 2026
Opinion Polls: From a Mirror of Electoral Sentiment to an Instrument for Shaping It
Opinion polls influence the political environment they seek to measure. By shaping perceptions of electability, they affect voters’ choices, media attention, campaign funding and access to electoral competition. The paper examines how these interactions can transform polling from a means of observing electoral sentiment into an instrument for shaping it. Its central finding is that influence does not require fabricated figures: selective publication, concealed sponsorship and the presentation of uncertain forecasts as assured outcomes can turn genuine data into a misleading account of public opinion.
Evidence across several countries illustrates how this influence operates. In the 2018 US General Social Survey, 23.6% of respondents considered spending on ‘welfare’ insufficient, compared with 73.2% when the question referred to ‘assistance to the poor’, demonstrating the significance of wording. During the 2023 Republican presidential debates, the minimum polling threshold rose from 1% to 6%, illustrating how measured support can become a condition for gaining the visibility needed to attract further support. The paper also examines how electoral expectations affect financial markets, drawing on India’s 2024 election and the controversy surrounding privately commissioned polling during the Brexit referendum.
The consequences extend beyond inaccurate predictions. Favourable polling narratives can distort campaign decisions, concentrate resources and narrow the alternatives visible to voters, while disappointed expectations can be exploited to undermine confidence in elections. Artificial intelligence introduces further risks through fabricated responses and synthetic substitutes for human participants. Nevertheless, the paper distinguishes methodological error from deliberate deception and argues that effective safeguards must preserve independent polling. Disclosure of funding, questions, sampling methods and weighting assumptions, alongside responsible reporting and independent scrutiny, can help ensure that polls inform electoral choice without presenting the outcome as predetermined.
Programmes
4 Oct 2026
Food or Fuel: The Implications of Biofuels for Global Food Security
The international system faces complex geostrategic pressures that place global supply chains under unprecedented strain. Escalating military tensions, particularly disruptions to shipping through the Strait of Hormuz, are putting pressure on oil and liquefied natural gas flows. In 2025, this passage carried around a quarter of seaborne oil trade and 19% of global trade in liquefied natural gas. These developments coincide with a shift in the Russia–Ukraine conflict towards attacks on energy infrastructure, alongside tighter restrictions on Black Sea shipping and disruptions to key export routes for strategically important grains. This convergence leaves the world caught between declining oil supplies and restricted access to part of the available food supply, complicating procurement and threatening the foundations of national security.
Faced with these shortages and rising shipping costs, some major powers and emerging economies are expanding biofuel production as an instrument of national policy to ease the energy crisis, alongside pursuing environmental objectives and supporting agricultural production. Agricultural producer countries are consequently choosing to redirect part of their strategic crop output, including maize, sugar cane and palm oil, towards biofuel plants to meet transport needs. This analysis advances the hypothesis that expanding biofuels derived from food crops may heighten the vulnerability of importing countries when demand growth outstrips the capacity of production and stocks to accommodate it, while trade policies restrict exportable supplies. The scale of this effect depends on the feedstocks used, the volume diverted and the responsiveness of production. It does not apply to the same extent to fuels produced from agricultural residues or used oils.
Import-dependent countries, particularly in the Middle East and Africa, may bear the cost of these pressures through diminished food security and domestic stability. An inability to secure food can, in this context, undermine social stability and signal the risk of political crises whose severity varies according to institutional effectiveness and the capacity to protect the most vulnerable groups. This complex situation poses an urgent question: how far can importing countries withstand the convergence of energy and food policies, and what protective mechanisms can safeguard their national security as competition intensifies between the use of crops for food and for fuel?
Publications
11 Sep 2026
Are Ports More Important Than Capitals?
While political capitals retain legal and sovereign authority, seaports have emerged as the "functional capitals" of the modern state. These maritime nodes are where sovereign decisions are translated into material reality, controlling the flow of energy, food, industrial inputs, and data. With 80% of global trade volume and 70% of its value moving by sea, the disruption of a major port can rapidly paralysise a nation's economy and military logistics, demonstrating that port power is highly consequential and systemic.
Port power is relational, depending on factors like geographic position, network centrality, industrial depth, and digital architecture. The global port network is highly concentrated, with less than 5% of ports handling half of the global maritime trade, creating a paradox where extreme efficiency leads to profound systemic vulnerabilities. This concentration makes ports susceptible not only to physical blockades or congestion but also to cyberattacks and climate change, necessitating robust resilience strategies.
Furthermore, foreign investment in port infrastructure carries significant geopolitical implications, moving beyond simplistic narratives of "debt-trap diplomacy". Long-term concessions and operational control can create strategic dependencies, even without outright asset confiscation. Additionally, modern ports possess a dual-use nature, where commercial facilities can provide latent military option value, blurring the lines between economic integration and naval expansion. Ultimately, true national power lies in the effective integration of the political capital's authority with the strategic port's physical capabilities.
This publication was written in August 2026
Programmes
23 Jul 2026
Bab al-Mandab at the Heart of the Crisis: Will the Houthi Blockade Push Pakistan into a Confrontation with Iran?
The Middle East is witnessing a new geopolitical crisis centred on the Bab al-Mandab Strait after Yemen’s Houthi movement announced on 20 July 2026 the imposition of a naval blockade on the Kingdom of Saudi Arabia, in application of a principle the group terms “blockade for blockade”. The measure comes as a direct response to the restrictions Saudi Arabia has placed on the airports and ports lying under Houthi control, most notably Sanaa Airport and the ports of Hodeidah, and the decision followed a military escalation that included strikes on Sanaa Airport and the launching of missiles and drones towards Saudi airports.
Through this closure the Houthis seek to transfer the cost of the blockade from the Yemeni interior to a corridor vital to Saudi Arabia in the Red Sea and the Bab al-Mandab Strait, by closing the strait to vessels flying the Saudi flag or bound for the Kingdom. The closure also coincides with the disruption affecting the Strait of Hormuz as a result of the ongoing Iranian–American war, where the Revolutionary Guard’s interception rate of vessels transiting the strait has reached some 89 per cent. This has driven the Kingdom over the past four months to reroute its oil exports westwards, moving 4.5 million barrels of oil a day through a pipeline to the port of Yanbu on the Red Sea in order to provide an alternative passage, an increase of close to fivefold on the period before the war began.
On another front, Pakistan faces a complex strategic position as a result of these developments, since Islamabad is bound by a mutual strategic defence agreement with the Kingdom of Saudi Arabia signed in September 2025, alongside the presence of Pakistani forces stationed in the Kingdom. The agreement stipulates that any aggression against either state is deemed an aggression against the other, while Islamabad simultaneously performs the role of diplomatic mediator between the United States and Iran, having sponsored the signing of a ceasefire memorandum of understanding between the two parties in June 2026. In this context, Pakistani officials regard attacks on Saudi Arabia as a red line, which makes the naval blockade not merely a problem touching Saudi security but a direct test of Pakistan’s ability to balance its role as mediator with Tehran against its military commitments towards Riyadh. This tension places the Pakistani leadership before a clear challenge and raises an important question as to whether it will persist in its neutral position, or move towards a firmer stance should the crisis develop into a regional confrontation affecting the interests of its Saudi partner.
Programmes
26 Sep 2025
The Global Economic Impacts of Starlink Outages: From Operational Fragility to Pathways of Resilience
In recent years, Low Earth Orbit (LEO) satellite constellations have emerged as a transformative layer within the global digital infrastructure, marking a departure from their original role as connectivity solutions for remote regions. These systems are now embedded within the operational cores of critical sectors such as civil aviation, maritime logistics, financial markets, and defence. The clearest manifestation of this structural shift is Starlink, operated by SpaceX, which by mid-2025 had exceeded 7 million users across more than 150 countries, with exponential growth rates in high-value, latency-sensitive industries.
This rapid technological and geographical expansion has positioned Starlink as a globally integrated utility—yet one that operates outside conventional regulatory regimes. It represents a structural concentration of control over global data flows in a single, privately held entity. The dual outages that occurred in July and September 2025 exposed deep systemic vulnerabilities within the Starlink network, including software architecture fragilities and environmental sensitivities to space weather events. These incidents prompted urgent questions about the stability of a critical infrastructure layer that now underpins sectors central to national sovereignty and global economic coordination.
This report interrogates the systemic risks embedded in the global economy’s growing dependence on LEO constellations through two interlinked analytical lenses. The first is a technical-political economy perspective, which examines the underlying architecture of the Starlink network and the typology of its failure modes—both endogenous and exogenous. The second is a forward-looking, scenario-based assessment that models the potential global economic consequences of a 24-hour Starlink outage in 2032. Through this dual approach, the analysis traces the contours of a new strategic dilemma: how to govern an emergent, transnational infrastructure whose failure could trigger multi-sectoral crises at planetary scale, yet whose design and control remain entirely privatized.
Programmes
23 Sep 2025
Structuring Power: Who Will Command the Future Map of Global Aviation
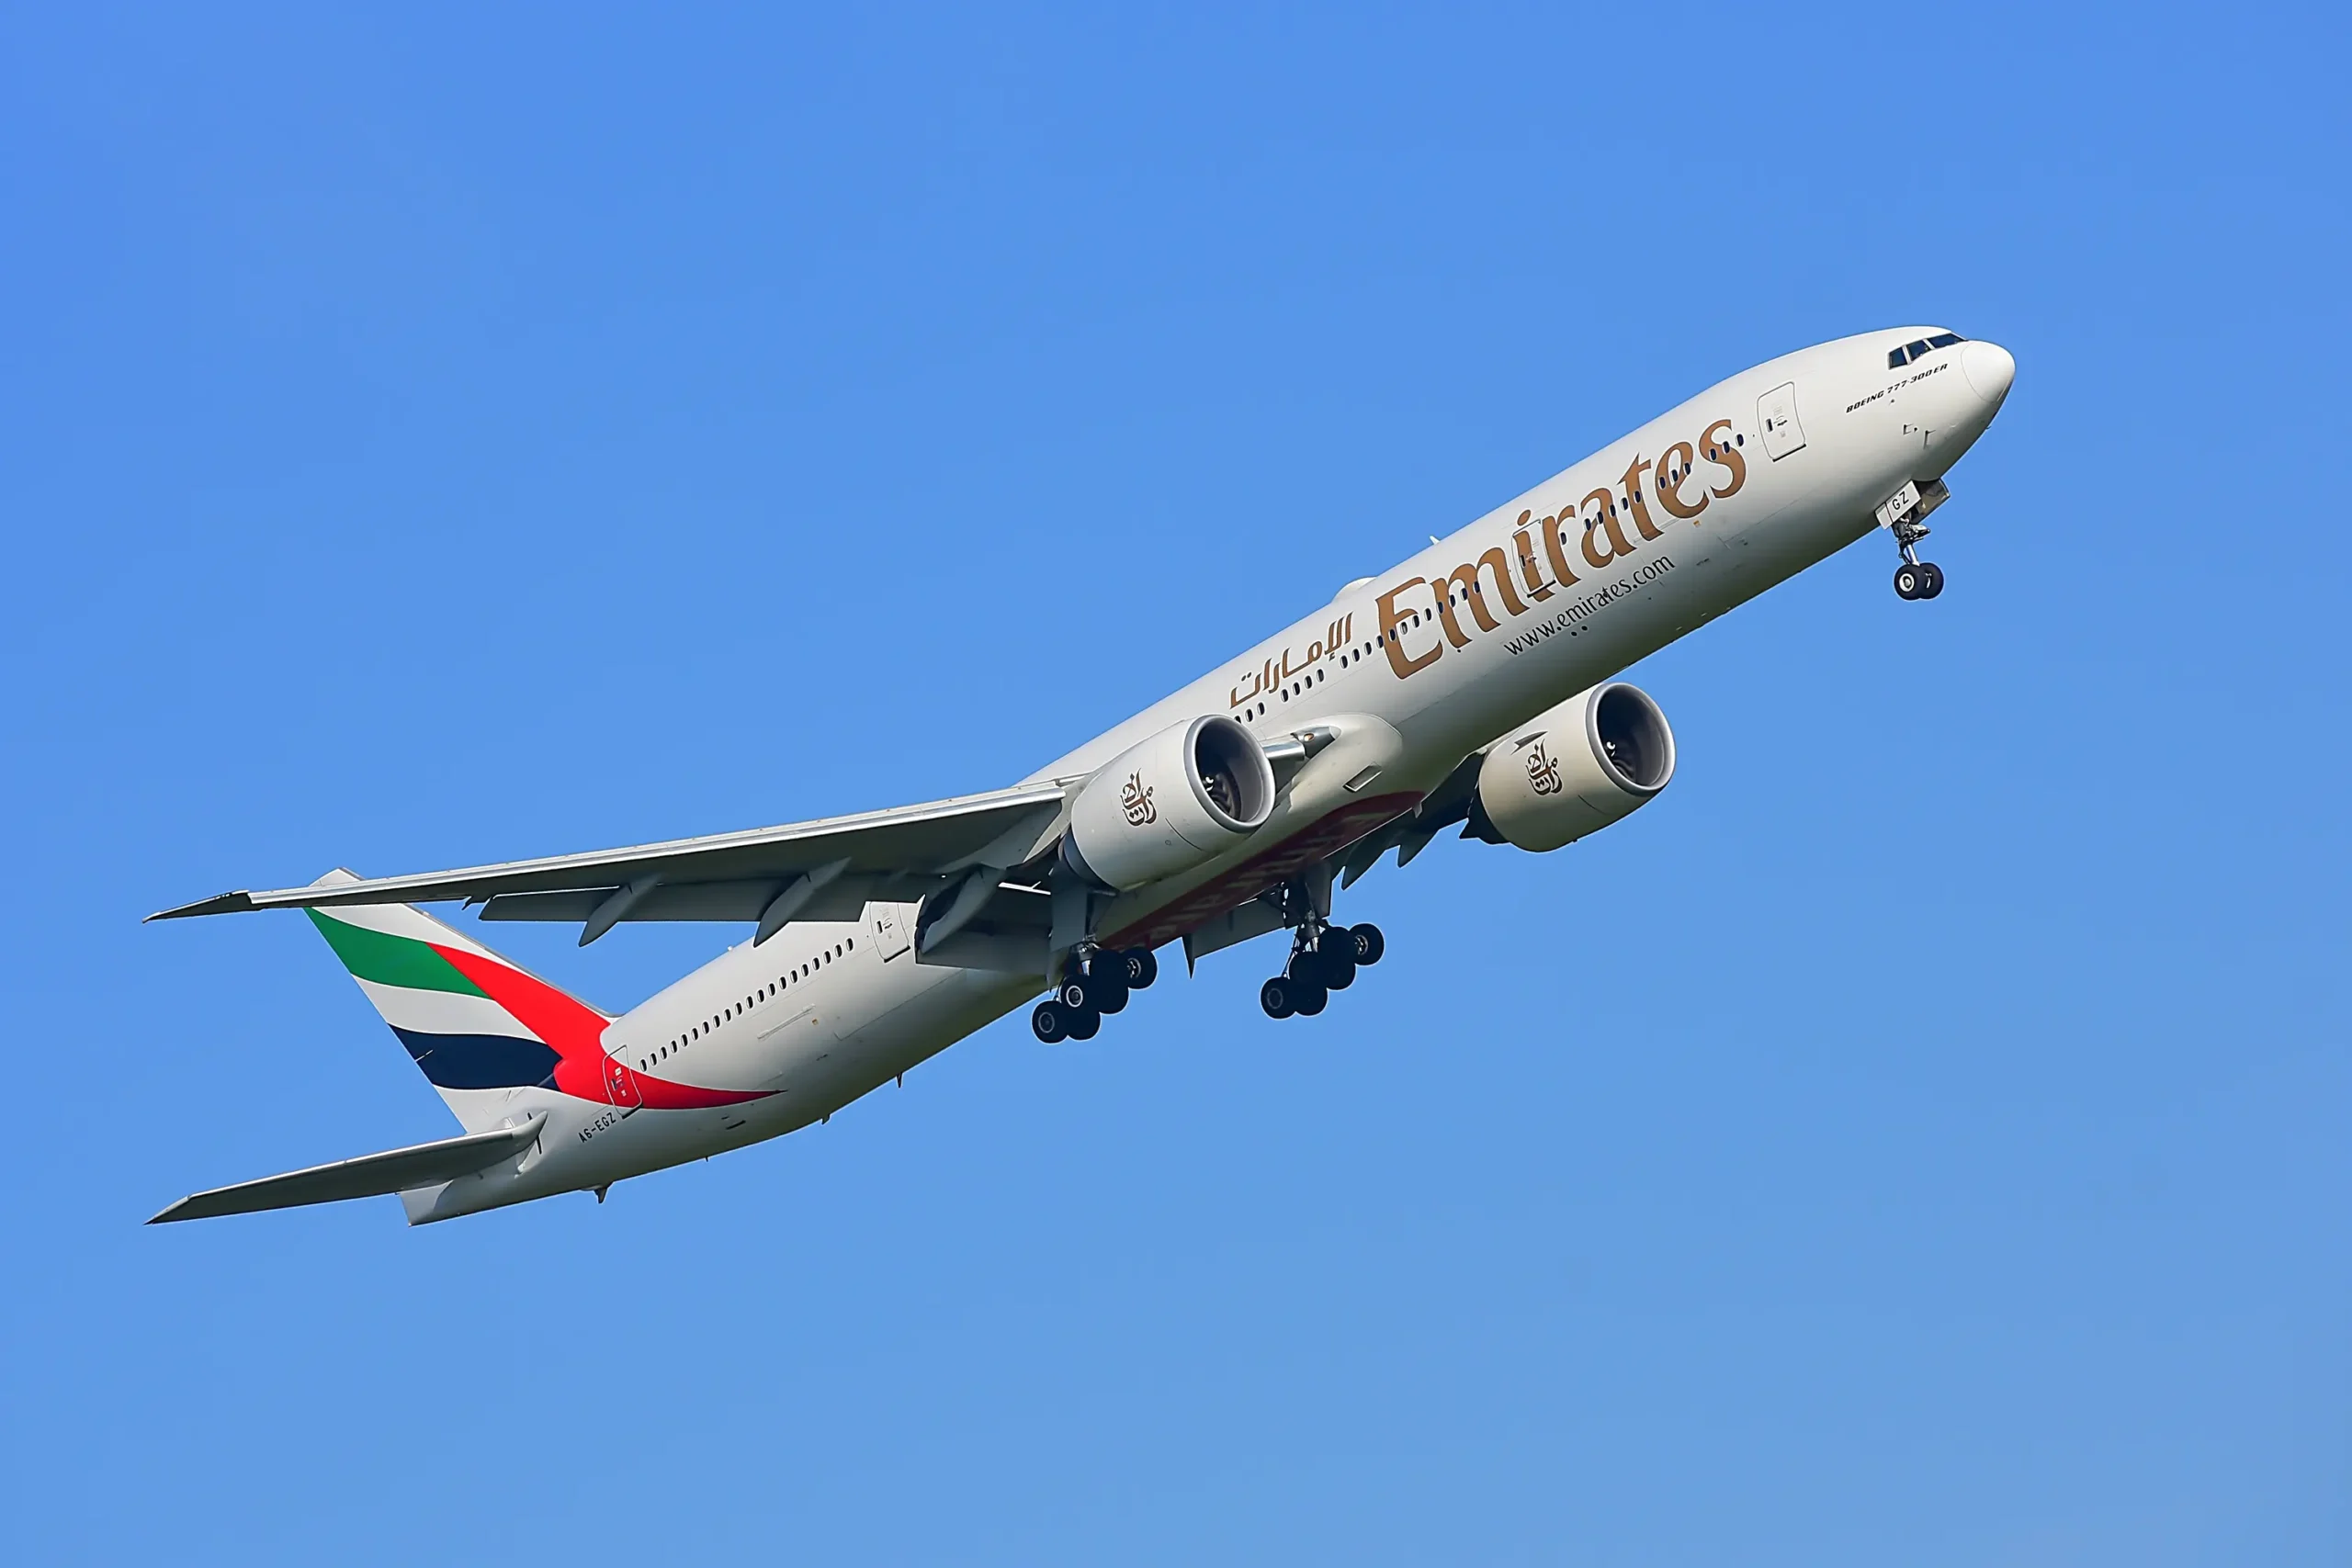
The global aviation industry is undergoing a historic realignment, as the center of gravity shifts decisively from West to East—a transformation that reflects deeper dynamics in the redistribution of economic and geopolitical power within the international system. For decades, Western carriers dominated the skies, leveraging superior infrastructure, extensive fleets, and mature consumer markets. Today, however, airlines based in the Middle East and Asia are emerging as the new engines of growth and connectivity, assuming a central role in redrawing the global map of intercontinental air travel. While the COVID-19 pandemic accelerated this trajectory, it did not initiate it; rather, it exposed the structural vulnerabilities of legacy Western airlines and underscored the strategic foresight of their Eastern counterparts, whose recovery was bolstered by extensive state support and institutionally anchored expansion strategies.
One of the most visible manifestations of this shift is an intense race to modernize fleets with next-generation, long-range, fuel-efficient aircraft—an investment wave that exceeds $200 billion in the Middle East alone. This is not merely a technical upgrade; it constitutes a deliberate, long-term vision to project aerial influence, enhance global market competitiveness, and entrench these airlines as sovereign instruments of statecraft.
Accordingly, this study analyzes the contours of this transformation through an integrated framework that examines operational strength, capital investment in fleets, network architectures, and the adaptability of business models. It further explores the growing convergence between national economic visions—such as Saudi Arabia’s Vision 2030 and China’s Belt and Road Initiative—and the strategic deployment of national carriers as tools of geopolitical influence. Rather than forecasting definitive outcomes, the paper seeks to situate this aviation shift within a broader, more volatile global context—one where profitability and efficiency increasingly intersect with sovereignty and strategic positioning, and where the skies themselves become arenas for shaping the balance of power in the decades ahead.
Programmes
18 Sep 2025
The Semiconductor Cold War: U.S. vs. Russia, China and India
The global competition over semiconductors and related military technologies has become the central axis of great-power rivalry. The United States maintains its leadership in the global semiconductor industry, with American companies securing roughly half of the global semiconductor market. However, this dominance faces a growing challenge from China, which accounted for 20% of global semiconductor sales in 2024. Beijing’s ambition to achieve self-sufficiency in semiconductors is steadily advancing despite ongoing trade tensions and intellectual property restrictions imposed by Washington amidst the broader ‘tech war.’ China aims to reach 50% self-sufficiency in semiconductor production by the end of the year, reinforced by significant investments in R&D and market expansion by Chinese firms.
In contrast, Russia’s position in semiconductor-dependent military industries is increasingly constrained. Although Russia retains expertise in weapons design, its reliance on imported materials and advanced chip-making equipment from Western countries exposes critical vulnerabilities. Western sanctions, introduced in response to Russia’s military actions in Ukraine, have sharply limited Moscow’s access to these essential inputs. In response, Russia has sought alternative suppliers, with China emerging as its largest source of semiconductor materials. These dynamic forms part of the broader Russia-India-China (RIC) trilateral framework, underpinning Moscow’s strategic pivot toward Eastern partnerships.
Meanwhile, India is rapidly evolving as a significant player in the semiconductor sector. The country’s announcement in September of its first indigenous chip, “Vikram 32,” marks a milestone in New Delhi’s pursuit of technological self-reliance and signals India’s potential emergence as a competitor to U.S. semiconductor dominance. India’s increasing engagement with Russia and China reflects a pragmatic alignment based on mutual interests, particularly in the context of escalating policy tensions with Washington. Notably, U.S. tariffs imposed on India’s trade in Russian oil have further incentivized this trilateral collaboration.
Collectively, the China-Russia-India “troika” represents a coalition of shared interests rather than a formal ideological alliance. Should this partnership strengthen, it could significantly bolster their semiconductor manufacturing capabilities and pose a formidable challenge to the American industry. Nevertheless, lingering frictions—such as unresolved border disputes, differing economic priorities, technological gaps, and the impact of sanctions—are likely to impede seamless technological integration. The United States still wields substantial influence over India, with opportunities to attract New Delhi through increased investments, tariff reductions, and advanced technology cooperation. Ultimately, the trajectory of the RIC semiconductor partnership holds profound implications for the global order. A successful integration of this “troika” chip industry with their respective military technologies could catalyse the rise of a multipolar system, revolutionizing surveillance, air defence, drone capabilities, and the broader defence industrial base, thereby reshaping international power dynamics.
Programmes
11 Aug 2025
Middle East in Energy Transition: From Stopgap to Global Architect
On July 28, 2025, during a joint press conference in Scotland with British Prime Minister Keir Starmer, U.S. President Donald Trump issued an unexpected ultimatum to Russia. He declared that the Kremlin had no more than 10 to 12 days (until approximately Aug. 8, 2025) to make tangible progress toward ending the war in Ukraine. Should Moscow fail to comply, Trump warned that President Vladimir Putin would face a sweeping package of economic sanctions and severe trade restrictions. This escalation came on the heels of prolonged diplomatic stagnation and Trump’s increasingly vocal frustration with Russia’s continued military operations.
Subsequently, on July 31, 2025, former Russian President and current Deputy Chairman of the Russian Security Council Dmitry Medvedev responded with a pointed and ominous message via his Telegram channel. In his remarks, he invoked the “Dead Hand”—Russia’s semi-automated nuclear retaliation system designed to launch a retaliatory strike even in the event of a complete decapitation of the nation’s leadership.
In response, President Trump ordered the deployment of two U.S. nuclear submarines to strategic positions, framing the move as a necessary precaution in the face of what he described as “extraordinarily dangerous” nuclear threats. Notably, he refrained from specifying whether the submarines were nuclear-powered only or also nuclear-armed—introducing deliberate strategic ambiguity and reinforcing the doctrine of pre-emptive deterrence through calibrated uncertainty.
What renders this sequence of events particularly significant is that the confrontation did not remain confined to the U.S. and Russia. Its repercussions quickly extended to India, which was thrust into the geopolitical crossfire. On July 31, the Trump administration announced the imposition of a 25% tariff on all Indian exports to the United States, accompanied by threats of further penalties targeting Indian firms that continue to purchase Russian crude oil or engage in defence cooperation with Moscow. The rationale behind this punitive action lies in New Delhi’s deepening energy relationship with Russia.
Although the Indian government has not officially announced any suspension of contracts with Russian suppliers, discreet directives were reportedly issued to state-owned refiners instructing them to explore alternative sources in the global spot market. This pivot has begun to materialize reflecting New Delhi’s attempt to maintain equilibrium between preserving its strategic autonomy and mitigating mounting U.S. pressure.
Yet the broader implications of this crisis extend well beyond geopolitical brinkmanship. What is unfolding is a systemic shock to the global order—one that is reverberating through energy markets, food security systems, arms trade corridors, and supply chains. The consequences will not be distributed evenly: while some Middle Eastern states stand to benefit from surging demand and price shifts, others may face acute vulnerabilities due to trade disruptions, inflationary pressures, or capital flight.
Programmes
17 Jul 2025
BRICS Summit 2025: Between Expansion and Caution
The 17th BRICS Summit convened in Rio de Janeiro on July 6–7, 2025, against the backdrop of accelerating geopolitical realignments. Under Brazil’s presidency, the summit sought to reenergize the bloc’s collective agenda, positioning BRICS as a more prominent actor in global affairs. Key declarations were issued, and the membership base was broadened—yet a cautious diplomatic tone accompanied these developments. The gathering appeared less as a turning point and more as a carefully choreographed exercise in articulating a shared vision for a multipolar world, tempered by the bloc’s internal complexities and external constraints.
Despite its symbolic achievements, the summit was marked by apparent limitations. The absence of certain high-profile leaders, coupled with underlying political divergences and institutional fragmentation, curtailed expectations for transformative decisions or a unified policy front. These constraints highlighted the gap between BRICS’s aspirations and its current capabilities. This analysis provides a focused examination of the outcomes of the 2025 BRICS Summit, assessing their implications for the evolving global order and the extent to which the bloc can credibly position itself as an alternative pillar in global governance.
Programmes
14 May 2025
What If: The India-Pakistan Ceasefire Collapses?
The recent U.S.-brokered ceasefire between India and Pakistan, following four nerve-racking days of escalating military exchanges, offered a moment of reprieve from the brink of what many feared could become an all-out conflict between the two nuclear-armed neighbors. Missiles and drones crossed borders, tensions were sky-high, and the language from both capitals was increasingly aggressive. President Trump's sudden announcement of a truce, while welcomed, underscored the inherent fragility of the situation. Amid celebrations in India and Pakistan, and self-congratulations in Washington, Kashmir endured another night of violence, with both sides claiming violations. This temporary calm exists against a backdrop of deep-seated historical grievances, unresolved territorial disputes, evolving nuclear doctrines, and a complex interplay of internal and external pressures. The critical question now is not just how the ceasefire was achieved, but whether it can hold, and what the consequences would be if this fragile truce were to collapse.

Programmes
19 Nov 2024
COP 29: Another Missed Opportunity for Action?
Despite a 2009 pledge to mobilise $100 billion annually by 2020, this commitment remains largely unmet, hindering adaptation and mitigation efforts. The 2015 Paris Agreement, while aiming to limit global warming, faces implementation challenges due to insufficient pledges and a lack of accountability. Developed countries, bearing historical responsibility for the climate crisis, must assume a leading role in mitigation and provide adequate financial support. Unfulfilled pledges perpetuate a cycle of vulnerability in the Global South, exacerbating the impacts of extreme weather events and rising sea levels. Climate change poses a challenge to sustainable growth in a number of industries and is not just an environmental concern. It is also an economic one. Insufficient investment for climate change exacerbates problems including growing debt in developing countries, decreased agricultural productivity, food insecurity, and volatility in sectors like tourism. These issues, which are linked to global accords like the Paris Agreement, are pressing and need to be addressed.

Programmes
10 Oct 2024
BRICS BRIDGE: Will Russia Reshape the Global Financial Order?
The world is currently experiencing rapid and significant geopolitical shifts, with rising global powers like the BRICS Group leading the charge to recalibrate the balance of influence within the Global Financial System. The recent expansion of the BRICS Group, now including 10 nations following the accession of Egypt, Saudi Arabia, the United Arab Emirates (UAE), Iran, and Ethiopia, underscores their growing influence. This bloc is unwavering in its determination to challenge the dominance of the U.S. dollar and to overhaul a global financial infrastructure that it sees as deeply flawed. The BRICS nations argue that the current system, with its structural flaws, serves as a tool for exerting political and economic pressure and contributes to the fragmentation of economies and regions by weaponizing trade and financial constraints.
The BRICS+ nations acknowledge that Dollar Dominance is underpinned by entrenched factors, most notably, the U.S. military power and global confidence in the U.S. legal and regulatory frameworks. Nevertheless, these nations are actively exploring alternatives to reduce their reliance on the dollar, aiming to bolster their financial sovereignty.
In pursuit of this goal, BRICS has ramped up efforts to reduce dependence on the dollar by employing innovative mechanisms. Chief among these is the proposal to issue a new, collective currency and establish a multilateral digital settlement and payment platform, dubbed as the “BRICS Bridge.” This platform is poised to foster greater trade integration among member states, particularly as some nations within the bloc, like Russia, face sanctions and exclusion from global systems such as the SWIFT System -The Society for Worldwide Interbank Financial Telecommunication-.
All eyes are now on the upcoming BRICS Summit, set to take place in October in Kazan. The summit is expected to showcase tangible steps toward implementing these initiatives, which could potentially redefine the structure of international trade and finance. The critical question remains: Will Russia and its BRICS allies break the dollar's stranglehold over the global financial order?