
Programmes
26 Aug 2026
Economic Outcast: The Limits of U.S. Secondary Sanctions Against a China-Insulated Iranian Economy
On 24 August 2026, the US Treasury announced an economic enforcement campaign under the name Operation Economic Outcast, designating close to 60 entities, individuals and vessels and issuing five unprecedented sectoral determinations under Executive Order 13902.1 Treasury Secretary Scott Bessent described the campaign as a comprehensive economic onslaught intended to sever every artery feeding the Iranian economy, while Iran's Minister of Economy, Ali Madanizadeh, dismissed it as an act of economic terrorism, insisting that his country has its own instruments and knows the rules of the game.
The significance of the campaign extends well beyond the number of designations. Washington is shifting its weight away from penalising Iranian entities and towards pursuing intermediaries in third countries: independent Chinese refineries, Gulf trading and exchange houses, and settlement channels operating outside the dollar. Yet the record since 2012 reveals a pattern that is close to invariable: sharp friction imposed from the American side, followed by structural Iranian adaptation, in which Iranian exports survive and the American stock of coercive power erodes.
This analysis therefore sets out to dissect the legal architecture of the campaign and identify what is genuinely new within it, then to test its six enforcement tracks against the structural obstacles Tehran has accumulated across four successive waves of sanctions, and finally to estimate the likely impact on the volume of Iranian exports, on the discount imposed on its crude and on the price path, while measuring the cost of compliance that financial and logistics hubs will have to absorb.
Programmes
19 Aug 2026
Digital Abundance, Experiential Scarcity, and the New Economics of Cinema
The theatrical performance of Christopher Nolan’s The Odyssey in July 2026 is a useful lens on a broader shift in media economics, though the film's box office alone cannot prove a structural thesis. While popular discourse frames the film's financial momentum as an isolated creative triumph, a microeconomic and corporate finance reading suggests a more durable market reallocation is underway: in an entertainment ecosystem saturated by digital abundance and on-demand streaming, consumer and studio spending appear to be reallocating toward physically differentiated experiences that are difficult to replicate digitally. This is best treated as a working hypothesis supported by suggestive evidence, not an established fact, one blockbuster’s run is not, by itself, proof of structural change.
This migration is commercially relevant to IMAX Corporation (NYSE: IMAX), whose model separates a broadly scalable global digital network from an ultra-scarce fifteen-perforation seventy-millimetre analogue footprint. Distinguishing these two tiers helps isolate how digital commoditization pressures studio differentiation strategy, shifts consumer willingness to pay, and concentrates box-office economics within a small number of specialized network operators, while also, exposing IMAX to risks that a purely optimistic reading tends to omit.
Publications
18 Aug 2026
Shadow Leverage Issue 3: The Regional Proxy Dilemma
Negotiations between Washington and Tehran are entering an increasingly complex strategic juncture, with most of the 60-day timeframe established under the "Islamabad Truce" having elapsed without a decisive agreement. This has been accompanied by renewed hostilities and the Strait of Hormuz once again closing to international shipping.
These developments on the ground coincide with intensive international diplomatic efforts to contain the repercussions of an open military conflict that has clearly weighed on regional and global economic growth.
At the heart of this negotiating landscape is the conspicuous absence of the regional proxy issue from both the draft preliminary agreement and the current talks. Rather than signalling that the issue has been sidelined, this absence raises fundamental questions about the future of the complex network that has for decades formed a central pillar of Iran's deterrence doctrine.
Current political dynamics suggest the proxy issue is no longer a secondary matter that can be deferred or ignored. Instead, it has become a structural fault line that cuts across each side's conception of security and stability, as well as the limits of any viable settlement.
Its exclusion from the initial formulations reflects a clear recognition of how difficult it would be to incorporate the issue without directly confronting red lines at the intersection of Iran's deterrence doctrine, the US vision of regional security, and Israel's efforts to translate military pressure into irreversible negotiating gains.
The dilemma takes on even greater significance in light of recent macroeconomic analyses indicating that the costs of proxy involvement have extended well beyond direct military losses, striking at the heart of the global economy. Proxy-related operations along critical maritime corridors, particularly in the Red Sea, have severely disrupted supply chains and inflicted tens of billions of dollars in losses on international trade through unprecedented surges in shipping and insurance costs. They have also created unconventional threats to the security of digital infrastructure, most notably subsea fibre-optic cable networks.
Security experts emphasise that the structural attrition the Axis of Resistance suffered during the intense confrontations of 2024 and 2025 prompted Tehran's leadership to reassess its tactics and instruments, but not to abandon them.
The crisis stems from a fundamental divergence in the actors' perspectives. Iran regards its network of proxies as a forward line of defence and an integral component of its national security, integrating these groups with its missile and drone capabilities. Washington and Tel Aviv, backed by regional powers, by contrast, view dismantling and disarming these groups as a mandatory precondition for any new regional security architecture.
This reality places the proxy issue at a critical intersection between three complex levels: Iran's pursuit of strategic depth for its defence; US efforts to neutralise sources of asymmetric threat; and regional and international concerns that link market stability and freedom of navigation to ending the activities of these groups around maritime chokepoints and in the Eastern Mediterranean. Any settlement that fails to define the place and functions of these proxies would therefore amount to little more than a fragile truce vulnerable to rapid erosion.
This section examines the divergent perspectives of the key actors on the regional proxy crisis. It assesses how these competing positions may clash or converge behind closed doors at the negotiating table. The paper asks a central question: will these discussions translate into strategic trade-offs that underpin a comprehensive and sustainable settlement, or will divergence between the parties' red lines reduce the anticipated agreement to little more than a temporary tactical freeze before an even more violent round of conflict?
This issue was written on August 2, 2026
Programmes
6 Aug 2026
Beyond Michigan: Is Abdul El-Sayed the Future of the Democratic Party?
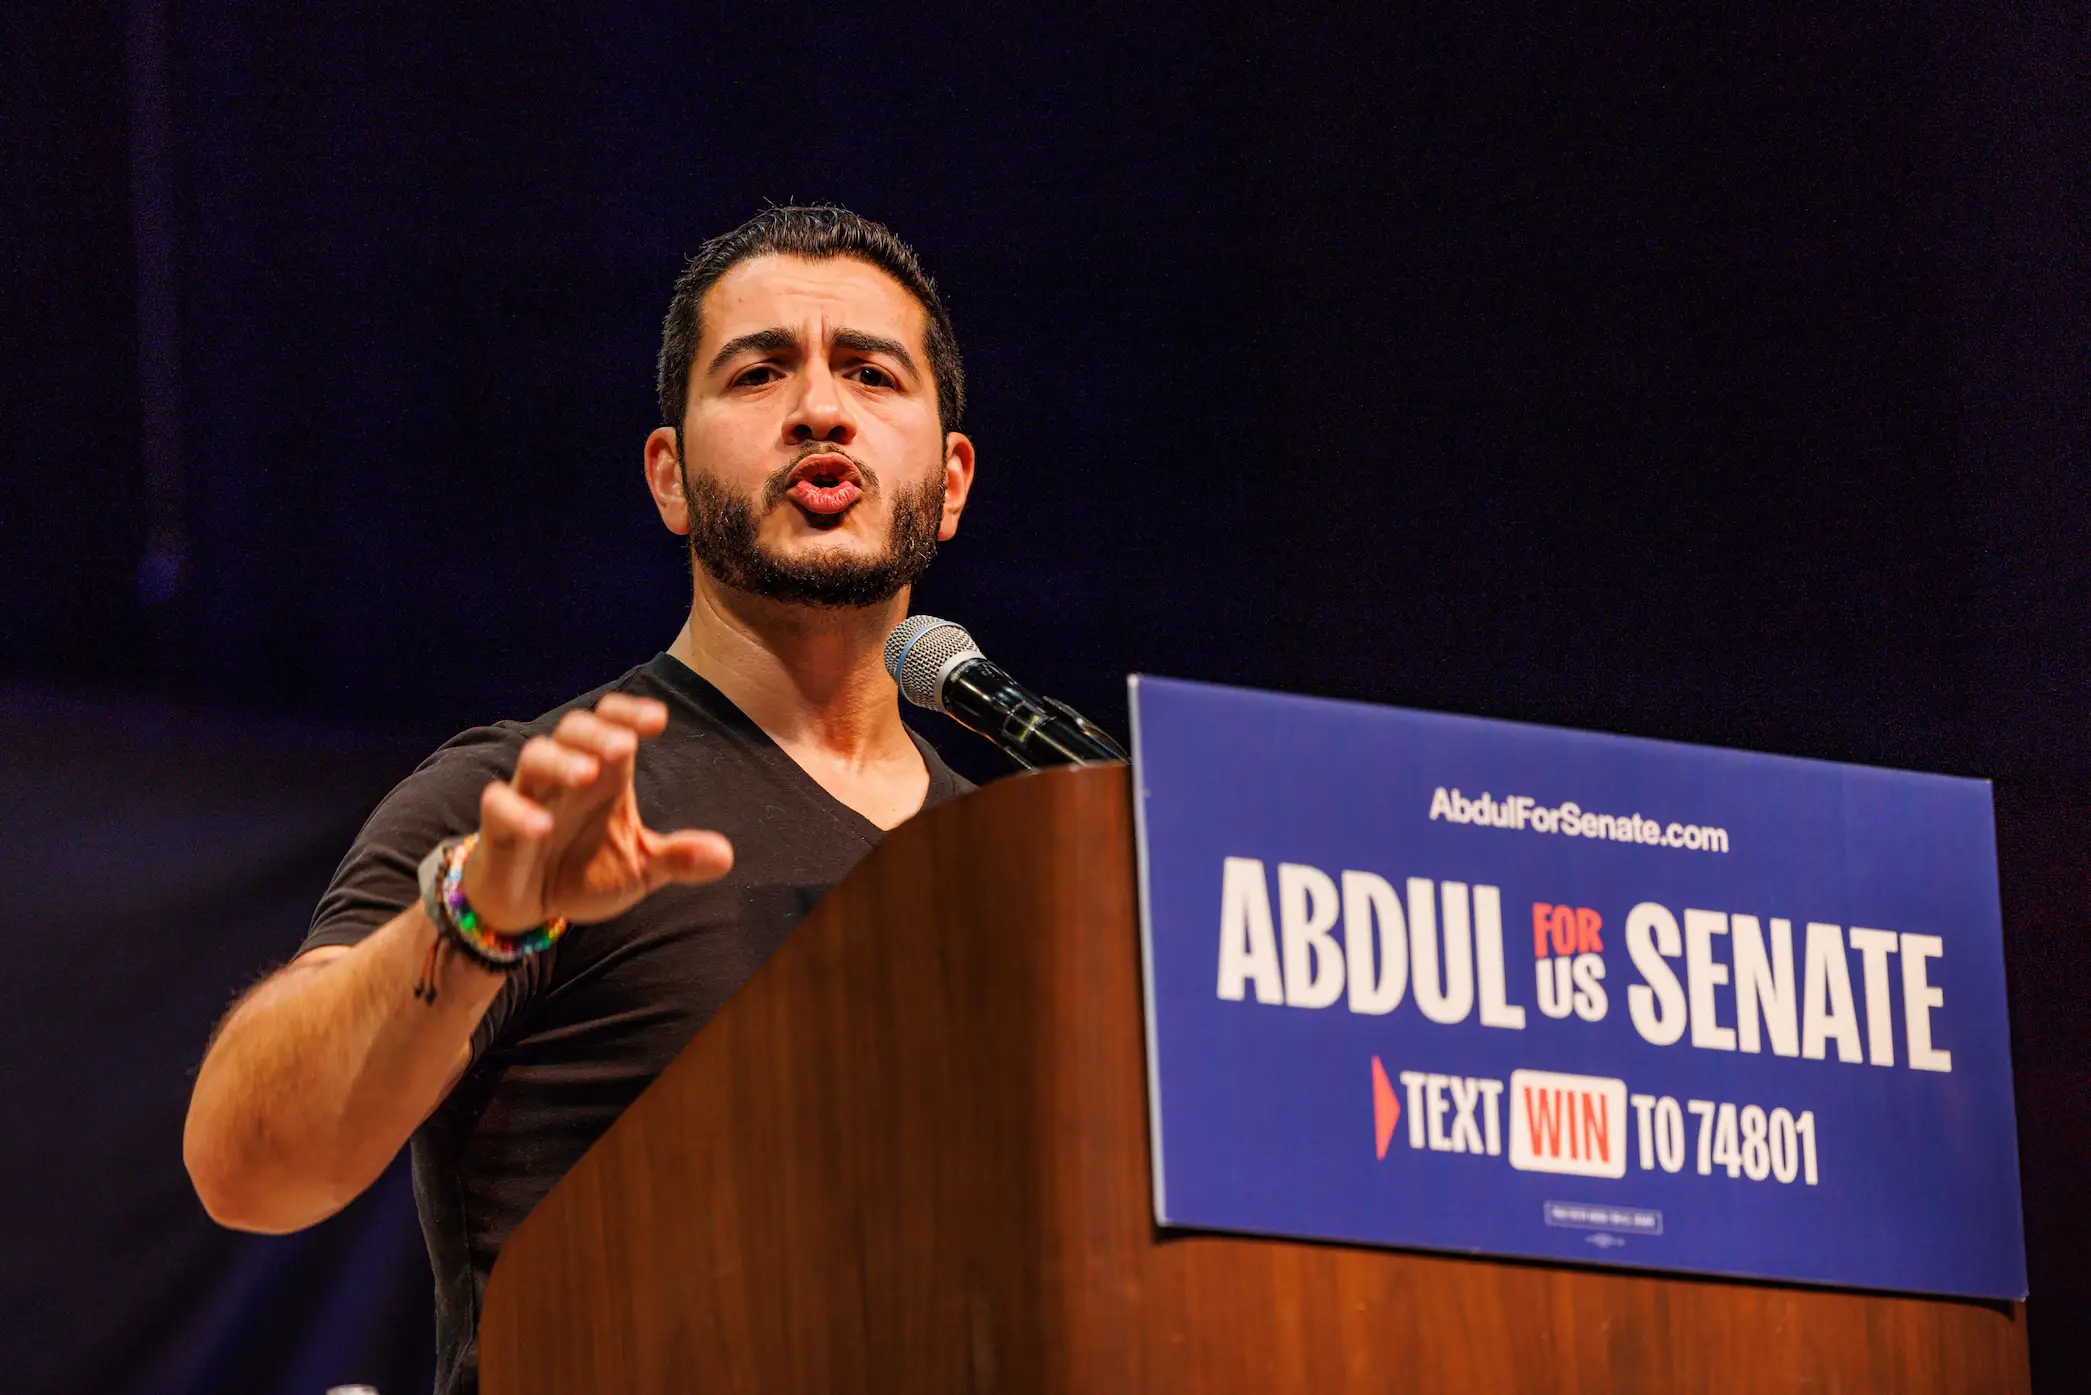
Michigan expected to deliver a Senate nominee on Tuesday night. Instead, it may have delivered the Democratic Party's most consequential ideological test since Trump returned to the White House. Abdul El-Sayed defeated Representative Haley Stevens for the party's Senate nomination against the wishes of much of the Democratic establishment, in one of the most expensive primaries in American history. His win immediately turned what had been treated as a routine state primary into a national argument over who actually speaks for the Democratic Party now. The bigger question, though, is not whether progressives can win a Democratic primary. It is whether Michigan just revealed where the party is genuinely heading, or whether it simply revealed what a narrow, highly engaged slice of primary voters wants, a distinction the party will need to answer honestly before November.
El-Sayed's win did not happen in isolation either. It followed Zohran Mamdani's insurgent rise in New York City, and it arrived on the same Michigan ballot as Rashida Tlaib's renomination and Donavan McKinney's defeat of sitting Congressman Shri Thanedar. Four results, one pattern. Together, they raise a question far bigger than any single race, whether Democratic voters are beginning to reject both the party's traditional leadership and its long-standing relationship with major donors, particularly on Israel and campaign finance.
Programmes
5 Aug 2026
Inside AI’s Quiet Takeover of the Midterms
The race to dominate AI is no longer being fought only in laboratories; It is now being fought at the ballot box. As the US struggles to establish comprehensive rules for one of the world's fastest-moving technologies, the companies developing it have begun competing over something even more valuable than market share, namely political influence. During the 2026 midterm election cycle, AI companies and their affiliated political action committees have poured tens of millions of dollars into congressional races, backed rival candidates, and expanded their lobbying operations across Washington. For the first time, elections themselves are becoming part of the battle over who will shape the future of AI governance.
This marks a significant shift in the relationship between technology and politics. Rather than waiting for governments to determine how AI should be regulated, leading firms are increasingly attempting to shape the political environment before those decisions are made. As Congress remains divided over comprehensive AI legislation, electoral politics has become another arena in the competition over AI. Consequently, the 2026 midterms may offer an early indication of whether democratic institutions can establish the rules governing AI before the industry's growing political influence begins shaping those rules instead.
Programmes
3 Aug 2026
The Economics of Reusable Launch Vehicles and the Competition over Low Earth Orbit
Access to low Earth orbit has undergone a structural transformation over the past fifteen years, shifting from a sovereign undertaking financed by the budgets of major states into a logistics service bought and sold by the kilogram. The global space economy reached roughly $626 billion in 2025, with commercial activity accounting for close to 78% of that total, and projections place it between $1 trillion and $1.8 trillion by 2035 — even though launch services on their own amount to no more than $14 billion. That disparity points to a basic truth: launch is not the market being contested. It is the gateway whose price determines the nature and the scale of everything that can be built beyond the atmosphere.
This structural shift rests on a single pivotal engineering innovation: recovering the first stage of the rocket and flying it again rather than discarding it after every mission. Recovery allows the capital cost of manufacturing to be distributed across multiple flights, and it demolished the price floor that had governed the market for decades. The consequence has been to narrow the technological contest over low-orbit reusability to two principal powers: the United States, which operates a mature fleet flying at an intensive and near-routine cadence, and China, which since mid-2024 has been conducting an accelerated, high-risk test campaign in pursuit of the same capability. The threshold of reaching orbit has therefore ceased to function as the technological dividing line between the two; the real remaining challenge lies in mastering precision guidance through the final metres before a safe landing.
Therefore, this analysis aims to unpack the economics of reusability and locate the true bottleneck within the cost structure; to then measure the gap between Washington and Beijing through two distinct indicators, namely the number of launches and the mass delivered to orbit; and finally to estimate the technical and temporal distance separating China from its first successful recovery, together with what its completion would mean for global launch pricing and for the budgets of the megaconstellations on which satellite internet services depend.
Programmes
27 Jul 2026
Trump’s Prize: How the July 2026 Tariff Package Installed the Middle East as a Global Manufacturing Hub
The global trading system underwent a fundamental transformation in July 2026, as the United States abandoned limited sector-specific protection in favour of a complex, multi-tiered tariff architecture that turned access to its domestic market into an instrument of economic and political pressure. Four major decisions converged within that single month. The first was the outright repeal of the de minimis exemption, which had allowed small consignments valued below eight hundred dollars to enter the country duty-free. The second was the application of the Section 301 forced-labour tariffs across two distinct bands, imposing 10% and 12.5% according to the compliance record of each partner state. The third was the activation of Section 338, a statutory provision that had lain dormant since the 1940s, to levy 50% duties on a range of Canadian goods. The fourth was the approval of a phased escalation reaching 200% on imports of generic pharmaceuticals.
The consequences of this package extended well beyond the raising of customs duties. They amounted to a comprehensive re-engineering of rules of origin and customs compliance requirements, which in turn altered the cost calculus of every manufacturer and supplier across global supply chains. This new reality pushed firms to search for alternative routes designed not merely to reduce transport costs, but to change the identity of the country of origin itself and so escape punitive duties. That search is precisely what turned the Middle East from a transit corridor into an industrial and logistical node positioned to play a pivotal role on the new map of world trade.
This analysis therefore aims to unpack the effects of the July 2026 package across three connected levels: its domestic cost to the American economy in terms of inflation, compliance friction and the feasibility of reshoring; the realignment of trading partners and the trade diversion and origin leakage that follow from it; and finally its direct implications for the economies of the Middle East and North Africa, together with quantitative estimates of price, investment and shipping trends through the end of the decade.
Programmes
13 Jul 2026
How Washington Built a De Facto AI Licensing Regime
President Trump returned to office with a clear promise to the technology industry, namely that the federal government would get out of the way. He had campaigned on dismantling what he called the Biden administration's overreach on AI safety, installed venture capitalist David Sacks as White House AI and crypto czar, and welcomed Big Tech CEOs to his inauguration as a signal of the partnership he intended.
For Silicon Valley, the message was unambiguous. The deregulatory era had arrived, and American AI companies would be free to race ahead of China without bureaucratic friction slowing them down. Almost 18 months later, those same companies cannot release their most advanced models without first receiving a phone call from the Commerce Secretary. The story of how that reversal happened, and what it means for US national security, allied trust, and the global AI race, is one the administration has never fully explained.
Publications
1 Jul 2026
Shadow Leverage Issue 1: Why the Strait of Hormuz Has Become the Decisive Negotiating Card
The Strait of Hormuz is no longer merely a disputed maritime passage, nor simply a recurring flashpoint between Iran and the United States. It has instead evolved into a central arena for testing the meaning of sovereignty in the region. While Washington continues to regard the strait as an international waterway governed by the principle of freedom of navigation, Iran’s Islamic Revolutionary Guard Corps treats it as a sovereign zone under its direct administration, subject to military rules imposed through effective ground control. Accordingly, the core of the crisis no longer centres on the question, "Is the strait open or closed?" Rather, the more consequential question has become: what is the future of the strait in light of the ongoing negotiations?
Recent developments, particularly following the Islamic Revolutionary Guard Corps’s threat to close the Strait of Hormuz in response to what it described as violations of the terms of the memorandum of understanding, especially about the Lebanese file just days after the memorandum was signed, reveal that the issue has not been resolved but has instead grown more complex. The memorandum treated the strait as a technical issue that could be managed through arrangements governing passage and transit to prevent friction. The Islamic Revolutionary Guard Corps, by contrast, approached it as a symbol of sovereignty, power, and the right to set the rules. This divergence rendered the understanding itself incapable of resolving the underlying dispute, because the disagreement between the two sides lies not in procedural details, but in who holds the authority to determine those procedures in the first place.
Although the United States and Iran agreed to reopen the Strait of Hormuz immediately after signing the preliminary agreement, this does not necessarily mean that maritime traffic will return to pre-war levels. Implementing this provision presents complex challenges related to the mechanism for reactivating the shipping corridor, the arrangements required to resume vessel traffic, and the restrictions that may persist during the sixty days allocated to negotiate the final agreement. These challenges are further compounded by the dispute over which party will assume responsibility for regulating and managing maritime traffic through the strait. Taken together, these obstacles suggest that reopening the strait may prove one of the most complex aspects of the agreement, particularly given the ongoing divergence between the American and Iranian visions for the future control of this strategic waterway.
The crisis surrounding the Strait of Hormuz, therefore, cannot be understood merely as a dispute over borders or the passage of ships; it is fundamentally a crisis of authority: the authority to set the rules, to impose exceptions, and to exercise the final say in determining whether this waterway remains open, closed, or conditionally accessible. For this reason, the question of the strait should no longer be viewed as a secondary file within the broader Iran–United States conflict. Rather, it should be recognised as one of the most consequential issues shaping and redefining the very concept of sovereignty, both within Iran itself and in the evolving structure of relations between regional and international powers.
Programmes
29 Jun 2026
Ankara’s Defensive Rise: A New NATO Path?
Turkey’s rise as a defence-industrial power is no longer a peripheral subplot in NATO politics. It has become a structural development with implications for how the alliance equips itself, how regional powers diversify procurement, and how strategic influence is exercised between Europe, the United States, and the Middle East. While much of the public discussion around NATO still revolves around burden-sharing targets and the Russian threat, a more consequential transformation is unfolding in parallel: Turkey is building a defence-industrial corridor that links alliance demand, regional export markets, and domestic technological ambition.
The timing gives this argument unusual weight. Turkey is set to host NATO leaders in Ankara on 7–8 July 2026, a moment that places its political role and industrial trajectory under the same spotlight. That summit matters not simply because it will convene alliance leaders in the Turkish capital, but because it comes after a period in which Turkey’s defence sector has expanded in scale, deepened in sophistication, and broadened its customer base across Europe, the Gulf, Africa, and Asia.
What emerges from this trajectory is not a Turkish substitute for NATO, nor a coherent anti-Western bloc inside the alliance. It is something more complex and, in strategic terms, more significant: an alternative source of military capability inside NATO that others can increasingly use when Washington or Brussels appear too slow, too restrictive, or too politically encumbered. In that sense, Ankara is not building a rival alliance. It is building an alternative industrial lane within the existing one.
Programmes
9 Jun 2026
The Petrodollar Myth: Why Architecture Beats Ambition
The petrodollar is one of the most invoked and least understood concepts in global finance. Since the 1970s, it has framed how analysts, journalists, and policymakers think about the dollar’s reserve status — equating America’s monetary supremacy with its energy arrangements. Yet this framing obscures more than it reveals. Dollar dominance is not a product of oil deals; it is the product of financial depth, legal architecture, and institutional trust accumulated over decades. To understand the future of global finance, one must look past the geopolitical theatre of energy pricing and examine the far more durable foundations that anchor the greenback at the centre of the global financial system.
The term "petrodollar" entered the global financial lexicon in the early 1970s, coined to describe the US dollars earned by oil-exporting nations following the 1973 Arab oil embargo and the subsequent surge in crude prices. Its origins, however, are rooted in a deeper structural shift. When President Nixon suspended the dollar's convertibility to gold in 1971 — effectively ending the Bretton Woods system, the United States (US) needed a new anchor for dollar demand. The informal arrangement that followed, most notably solidified through US-Saudi negotiations in 1974, ensured that Gulf producers would price oil exclusively in dollars and reinvest their surpluses into US Treasury bonds and American financial markets.
For decades, this arrangement fed a compelling narrative: that the dollar's global supremacy was underwritten by oil. The logic was straightforward since every oil-importing nation needed dollars to purchase energy, global dollar demand was structurally guaranteed. Any challenge to this system, the argument goes, would directly erode the dollar's reserve currency status. This view gained traction among geopolitical analysts and alternative media circles, especially following Saddam Hussein's 2000 decision to price Iraqi oil in euros, and later amid speculation that US military interventions in the Middle East were partly motivated by protecting the petrodollar system.
Yet this narrative, however widespread, rests on a fundamental misreading of how dollar dominance functions. The Economist challenges it directly, arguing that the petrodollar is often misunderstood and is no longer the primary pillar of dollar strength. The volume of oil traded globally, while significant, represents only a fraction of total dollar-denominated transactions. According to the Bank for International Settlements, the dollar is involved in nearly 88% of all foreign exchange transactions worldwide, a dominance that reflects financial depth and institutional trust, not energy dependence.
Historically, the oil-dollar link carried greater weight when global financial markets were less integrated, and US Treasuries represented the default safe asset for a narrower set of alternatives. That structural context has fundamentally changed. The dollar's role today is upheld by the unmatched liquidity of Wall Street, the enforceability of American contract law, and decades of accumulated creditor confidence — foundations far more durable than any bilateral energy arrangement. The petrodollar, in short, was never the dollar's load-bearing wall; it was, at best, a single supportive beam in a much larger structure.
Programmes
4 Jun 2026
World Cup 2026: When Sport Exposes the Fault Lines of Politics
The successful joint bid by the United States, Canada and Mexico to host the FIFA World Cup 2026 was widely welcomed in international diplomatic circles, regarded as an exceptional achievement in cross-border sports diplomacy. Through the "WE ARE 26" slogan, FIFA and the host countries sought to present an image of regional cooperation and shared cohesion, promoting the idea that the soft power of sport could prevail over complex geopolitical differences.
Yet by the summer of 2026, these promises had collided with a completely different political reality. Rather than reflecting unity, seamless movement, and open borders, preparations for this major event revealed deep divisions and strict security measures across North America. As a result, the World Cup shifted from being an instrument of regional integration to a magnifying lens exposing the sharp political contradictions that shape the domestic and foreign policies of the host countries.